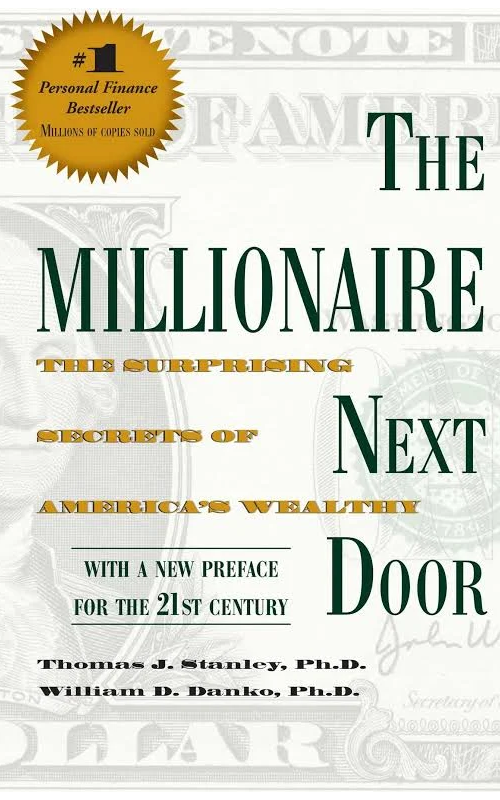
On podcasts I follow these days, usually personal improvement, or financial management improvements, one of them suggested to read through The Millionaire Next Door (Audio Book lower cost on Amazon). I looked at the books reviews, and just felt I needed to read it. So, I picked it up, and read through it, delaying my Novel November (oops). I can highly recommend this, alongside Rich Dad, Poor Dad.
I’m not a financial advisor, this is not me giving financial advice, I just want to share some ideas to consider, which I’ve seen over the years through the books I’ve read.
The first interesting note, in the introductory pages, was the idea of what all millionaires seem to do: On average, they invest nearly 20% of all income every year.
Not to point fingers at anybody, this is only my observation. Every day I see many people around me complain of the fact that they’re “broke,” yet they keep buying expensive things. The Millionaire Next Door explains the reason this occurs in so many ways.
I’ll give the short-hand summary of an example: with their flashy expensive cars bought with massive loans, massive other debts, and random expensive purchases that they seem to fast get bored of, they dive into this rabbit hole. A few even complain they barely have any savings, or investments. They just despise considering the fact they’re the reason they’re in financial distress.
What I recommend to others, who hear me regularly use the curse word (broke) as my excuse to try never buy pointless things: save with consistent returns. Just consider my previous reading reviews of Become Your Own Financial Advisor, and How to Buy Your Hapiness.
That means R100 saved get under 50 cents in the first month, adding R100 each month and compounding to ~R1200 at the end of the year. Yes, that’s too slow, inflation is growing around there at present, so it barely has growth, unfortunately.
Begin earning and investing early in your adult life.
The Millionaire Next Door, p75
The book agrees, your low interest bank savings can be your emergency fund. Though, try get closer to 10% p.a. if possible, as it means growth above inflation is possible. Your investments are for your future. They give a few interesting adaptions for where you can consider yourself, to put it lightly, ask yourself, are you a:
- PAW – Prodigious Accumulator of Wealth: Net Worth 2x expected
- AAW – Average Accumulator of Wealth: roughly expected Net Worth
- UAW – Under Accumulator of Wealth: actual Net Worth less than half expected
I wont go into too much detail, but it’s something you should consider for where you are in life. Net worth, is assets minus liabilities. That’s “home equity + investments + retirement + business equity + cash” as the assets, and “morgage, loans, credit, etc” the liabilities (any money you owe, of course, always lands here). Your Net Worth in the AAW middle ground sits at “(your-age * your-annual-income)/10“.
If you are in UAW you have a large amount to catch up on, but you can hopefully pick up from where you find yourself, for a better future.
1. Do you know how much your family spends each year for food, clothing, shelter?
The Millionaire Next Door, p78
2. Do you spend a lot of time planning your financial future?
3. Are you frugal?
They have several case studies where they compared families, all earning in the 7 figures. A section has a case study that uses the questions shared here. If you have 3x YES for yourself, you are headed in the right direction. I wont ask the people mentioned in the 3rd paragraph for their 1 or 2 answers, but they are obviously a resounding 1x NO to being frugal. Yeah, you can enjoy the brand new expensive gadget you bought yourself until you get bored of it, not for me.
People can do what they please, just consider it. I prefer to make my own lunch, it averages out to R30 per lunch meal. In 4 weeks, instead of R60+ meals Monday to Friday, it saves over R600 (20x R30+) when around lowest cost. Yes, that savings I do my best to push into my savings, or investments. I’m not perfect, I do break that, at times.
Even bulk frozen meals are debatable, they’re good – but a higher loss, the work out to R100+ usually; yet you can buy the ingredients, cook the meat and veg yourself, and freeze it for yourself. Sure, you don’t enjoy cooking, but I could plan for 2 hours a week I prepare these meals and put them in containers, and when cool enough put them in my freezer.
Getting ingredients for myself I can spend ~R225 (1 person, assumed on 8-10x Chicken breast ~R110 + 2x Large 1kg frozen veg bags ~R115) and create 8-10 split containers of chicken and mixed veg for a whopping R23-R29 frozen meal. That’s 4 to 5 days dinner and lunch covered. Then with 2 hours every weekend you can just replenish the supply, and even change up your frozen meal choices, these frugal healthy meals cost you only around R1575 per month.
This isn’t to share you need to cook and freeze things, no, just get the different meats you want, the different greens for max 1 week supply for 1 to 2 people, and you can just get an air-fryer, learn how to spend 2 minutes prep, toss it in, turn it over halfway (not pizza though), and voila – you lost on 3 minutes of your day cooking. Also, a dietician might share you also need other things versus the chicken example above, but I hope I made it understandable.
A near frugal way to look at fast meals for yourself, so I can spend my time off work studying, or working on my hobby projects, or at times when I need a break doing other enjoyable activities. Heck, when you don’t even feel like the 3 minutes to cook, you could have prepared a few frozen meals on a 2 hour weekend window, you can then just defrost it when you don’t feel like cooking. Perhaps? Heck, even frozen pizza fits this bucket for me at times (though, cooked using my air fryer, this is tough to find the sweet spot though).
See, this isn’t full frugal, just smart planning. Buy bulk instead of the smallest ingredients for each meal, or buying takeaways. If you just do this, the small R600 saved every month can be put into a decent 8%+ savings and be over R7.5k for your end of year “fun money” if you’d like. Or, yes of course, left added to your net worth alongside the 20% you invested already. Surely, you had a portion saved in the 6-10% p.a. savings each month, planning for your holiday already with small monthly contributions, so this could just be added to your investments?
Whatever your income, always live below your means.
The Millionaire Next Door, p161
Just to emphasize it, I think it might be cool to get a Switch some time to play games on. First, I will rather buy it second hand. Second, I have enough games for entertainment on computer already. Third, I see a second hand Switch for R3.5k today, but I rather consider if I invest that rather – R3.5k at 8% p.a. is ~R780 growth in year 1, then in 30 years is approximately >R35k invested. No thanks, I don’t need a Switch, honestly.
Rather than buying something cool, which will fall into a drawer somewhere in the house and you wont play for years, get your money to work for YOU! I definitely recommend The Millionaire Next Door as well, a great way to look at the idea behind finance and wealth, from both sides of the spectrum. Money wasted isn’t as good as people make it seem, you don’t need to show others you can afford luxuries that are pointless.
With that, it’s time for me to catch up on the hours I missed each day in the Novel November challenge #1. At 11 hours missed, for the next 11-12 days, I will do 2x single hour sprints each day, to catch up.